Debt Snowball Worksheet Printable (Free PDF)
WHAT IS THIS DEBT SNOWBALL WORKSHEET? The debt snowball is the payoff method that actually gets finished: you list every debt from smallest balance to largest, pay minimums on all of them, and throw every extra dollar at the smallest one until it is gone — then roll that payment into the next smallest. The…
WHAT IS THIS DEBT SNOWBALL WORKSHEET?
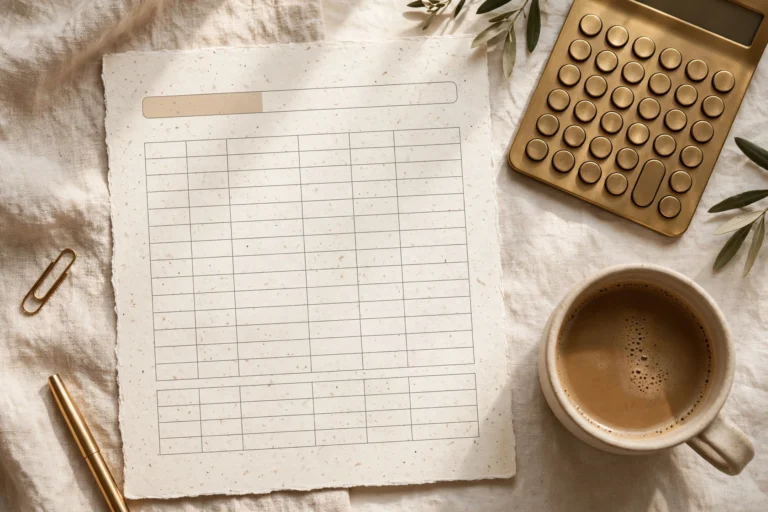
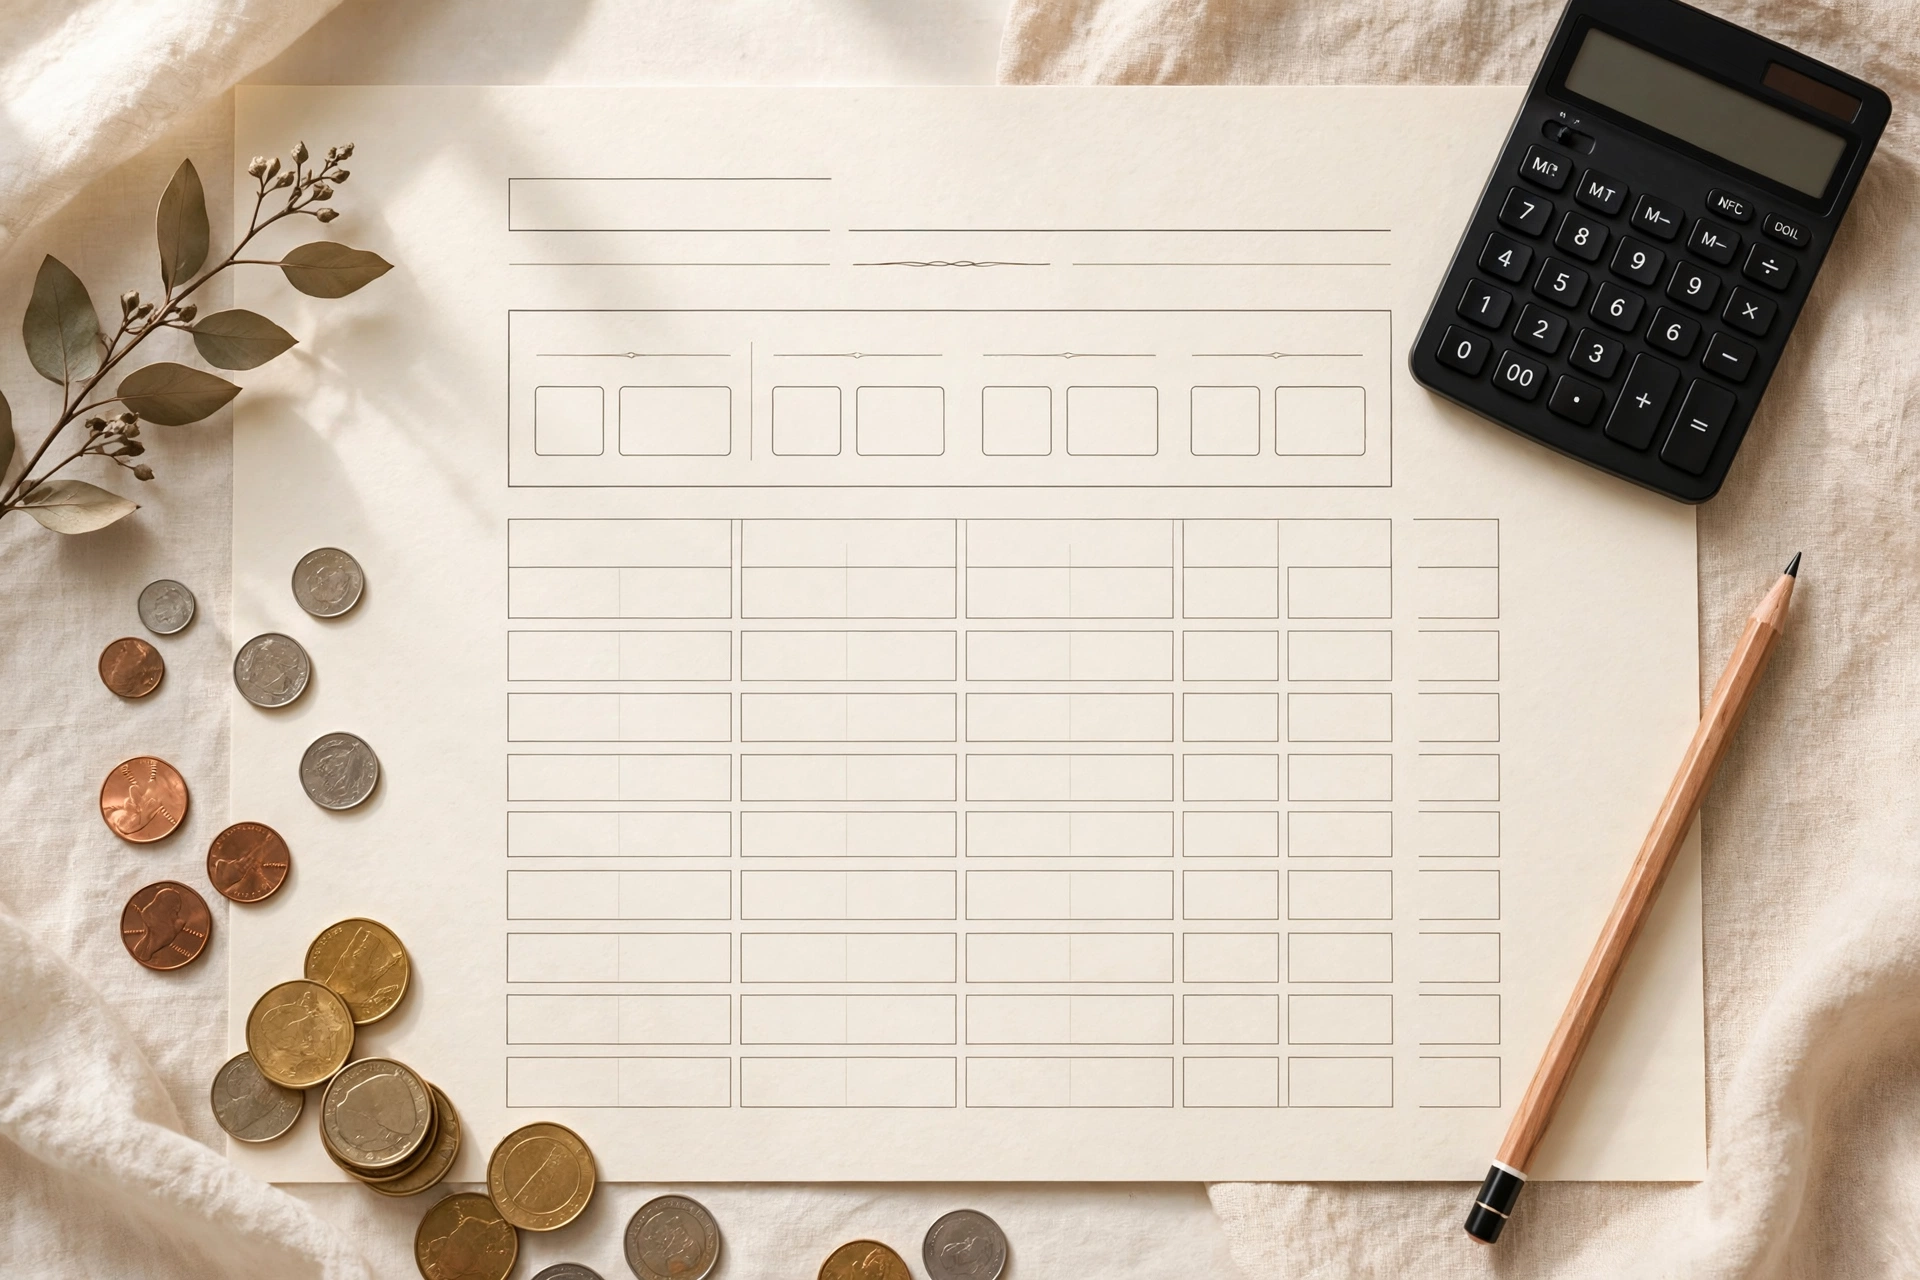
The debt snowball is the payoff method that actually gets finished: you list every debt from smallest balance to largest, pay minimums on all of them, and throw every extra dollar at the smallest one until it is gone — then roll that payment into the next smallest. The balances shrink, the wins stack up, and the payment grows like a snowball rolling downhill. This free debt snowball worksheet printable gives you the whole plan on one page: a table for up to ten debts with balances, minimums, rates and payoff order, plus a progress section to track each kill. This debt snowball worksheet is free to download – print as many copies as you like.
It is for anyone carrying more than one balance — credit cards, a car loan, medical bills, student loans, buy-now-pay-later tabs — who wants a plan instead of a pile of minimum payments going nowhere. If you have ever paid minimums for a year and watched the total barely move, this sheet is the antidote: it turns the vague dread of “debt” into a numbered hit list.
There is a rival method worth knowing, and the sheet explains both. The avalanche method targets the highest interest rate first, which saves the most money mathematically. The snowball targets the smallest balance first, which wins psychologically — and psychology is what finishes payoff plans. Research on debt payoff keeps finding the same thing: people using the snowball method are more likely to actually become debt-free, because early wins keep them going. Unless your rates are wildly different, pick snowball. The best method is the one you will still be doing in month nine.
Pair this worksheet with our debt payoff tracker — the worksheet is the battle plan, the tracker is the daily log of every balance on the way to zero. And our monthly budget sheet is where the extra payment money comes from each month.
Table of Contents
WHAT’S INSIDE THIS DEBT SNOWBALL WORKSHEET
DEBT LIST TABLE — TEN ROWS
One row per debt: creditor name, current balance, minimum monthly payment, interest rate, and a payoff-order number you assign after sorting smallest to largest. Ten rows cover most households; if you have more, print a second sheet and keep them together. Writing every balance in one place is the hardest and most valuable step — most people underestimate their total until they see it summed.
PAYOFF ORDER COLUMN
After listing, number the debts 1 through 10 in payoff order — smallest balance gets number 1. This column is the whole strategy made visible: when in doubt about where the extra money goes, it goes to the lowest un-crossed number. No decisions, no willpower, just the list.
SNOWBALL PROGRESS SECTION
A kill list: each debt gets a line where you write the date it hits zero and the new snowball payment total. Watching the payment grow — $85 becomes $140 becomes $260 — is the most motivating math in personal finance. The sheet makes you record it, because the growing number is what carries you through the boring middle months.
SNOWBALL VS. AVALANCHE EXPLAINER
A short printed box on the sheet itself: snowball = smallest balance first (fastest wins, best for motivation), avalanche = highest rate first (least interest paid, best math). One paragraph each, so the strategy lives on the page you are actually using instead of in an article you read once.
HOW TO USE THIS DEBT SNOWBALL WORKSHEET
- List every debt you owe: credit cards, loans, medical bills, everything with a balance. Pull actual statements — guesses are how debts hide. Write the creditor, balance, minimum payment, and rate for each.
- Sort by balance, smallest first, and number the payoff order. Ignore the interest rates for now — order is by balance. This feels wrong to the math brain and right to the human one. Trust the human.
- Build your budget so every debt gets its minimum paid on time, every month. Our monthly budget sheet is the tool for this — the snowball needs the minimums covered before it can roll.
- Find your extra payment amount — even $25 counts — and aim it all at debt number 1. Everything else gets minimums only. One target, full focus.
- When debt number 1 hits zero, celebrate briefly, then add its old payment to the extra amount and aim the new total at debt number 2. Record the new snowball total on the sheet. This is the moment the method earns its name.
- Repeat until the list is crossed out. When a setback hits — and one will — do not restart the plan, just resume it. The order is still right; only the timeline moved.
PRINTING TIPS
Print at “Actual size” or 100 percent scale so the table columns keep their widths and your handwriting fits. This sheet gets updated monthly as balances drop, so print on 100 GSM paper or laminate it and update figures with a dry-erase marker. Keep it where you pay bills — next to our bill payment tracker is ideal. Both A4 and US Letter versions are included. The black-and-white design prints cleanly on any home printer.
FREQUENTLY ASKED QUESTIONS
Is this worksheet really free?
Yes. The PDF is free for personal use in both A4 and US Letter sizes. Print a fresh copy whenever your balances change significantly.
Snowball or avalanche — which should I actually pick?
If your highest-rate debt is also close to your smallest balance, the question answers itself. Otherwise: pick snowball if you have ever quit a payoff plan before (the quick wins keep you in), pick avalanche if you are certain you will stick with it for the full term and want to minimize interest. Most people should pick snowball.
What if I can only afford minimums right now?
Then the worksheet still helps: list everything, get the order right, and pay minimums on time while you work on freeing up extra cash — our monthly budget sheet is built for exactly that. The snowball starts the month you find your first extra $25.
Do you have other money planners?
Yes. Our debt payoff tracker logs every balance monthly on the way to zero, our budget binder gives each month an at-a-glance dashboard, and our 52-week savings challenge builds the emergency fund that keeps you from re-borrowing. Your debt snowball worksheet is ready below in both A4 and US Letter.
DOWNLOAD YOUR FREE DEBT SNOWBALL WORKSHEET
Every debt-free person started with a list. Download the free debt snowball worksheet printable PDF below in A4 or US Letter, write down every balance tonight, and number your hit list. Debt number 1 is closer than it looks.
Free forever · No email needed · A4 + US Letter included.